One couple wants to stop living paycheck to paycheck. A big obstacle: Nearly $40,000 in credit card debt

Daftar Isi
A Milwaukee Couple Confronts $40,000 in Credit Card Debt While Planning for a Different Future
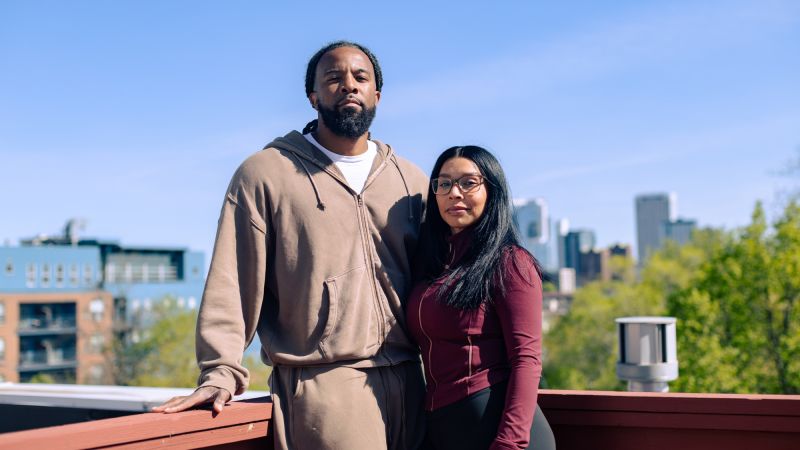
Activelifezero.com – Mariza and Geffrey Gordon want to move beyond the strain of covering expenses from one paycheck to the next, but they face a daunting starting point: almost $40,000 in credit card balances.
The Milwaukee couple entered a financial coaching challenge while both were employed. Shortly afterward, Mariza learned that her job would be eliminated and that she would receive only two months of severance. The change added urgency to a financial situation already shaped by several debts and high monthly card payments.
Much of the couple’s credit card debt came from paying for their wedding last year, Mariza said. Their required minimum payments total about $1,400 a month, a sum that can make it difficult to build savings, reduce principal balances quickly or prepare for unexpected costs.
Focusing on the Most Pressing Financial Burden
Budgeting expert and financial educator Tiffany Aliche met with the Gordons for their first consultation. She was struck by the way they approached the situation as a team.
“They were so supportive of each other,” Tiffany said.
She also identified a decision that she believes puts them ahead of many people facing financial stress: they sought guidance rather than allowing the problem to remain unaddressed.
“Seeking help. A lot of people just stay stuck,” she said.
Because the coaching period is limited, Aliche concluded that the couple should not try to solve every money concern at once. Instead, she focused on the issue creating the greatest immediate pressure: their revolving credit card debt.
Minimum payments can keep an account current, but they may leave little room in a household budget. For the Gordons, the monthly total was consuming money they hoped to direct toward larger goals. Their challenge is not simply eliminating balances; it is creating enough financial stability to avoid relying on new debt when life changes unexpectedly.
Looking Beyond a Debt-Free Moment
Before reviewing detailed budget choices, Aliche asked Mariza and Geffrey to imagine the life they would like to have 10 years from now. She calls the exercise “dreamscaping.”
The purpose was to shift attention from the immediate anxiety of bills toward a clear reason for making difficult financial decisions. Aliche noted that becoming debt-free, by itself, does not automatically create financial security or wealth.
“I wanted to give them something to work (toward),” Tiffany said.
Her larger message was that a household can have no debt and still lack savings, investments or a plan for long-term financial growth. For the Gordons, reducing debt is therefore one part of a broader effort to build a more durable financial life.
“Let’s get to a point where you don’t feel like your debt is drowning you. But the true goal is to grow wealth,” Tiffany said.
The couple responded strongly to the exercise. Mariza said they had been so overwhelmed by current pressures that they had not spent much time considering what they wanted in the years ahead.
“We were so caught up in the now and stressed about the present we hadn’t put thought into what we want for the future,” Mariza said.
Their vision includes owning a home, purchasing an investment property, taking occasional vacations, launching businesses and contributing to individual IRAs in addition to their workplace retirement plans. Those aspirations give the couple a framework for evaluating debt-payoff options: a plan must lower pressure today without undermining their ability to manage future needs.
Exploring Debt Repayment Options
Aliche encouraged the Gordons to build a budget spreadsheet and investigate possible routes to repaying their balances. She suggested contacting the National Foundation for Credit Counseling, as well as checking whether a lower-rate personal loan or a balance-transfer card could help.
The National Foundation for Credit Counseling presented a potential five-year repayment arrangement with monthly payments of $900. That would reduce the couple’s monthly obligation by $500 compared with the minimum payments they currently make.
However, the plan also came with an important restriction: they would not be able to use revolving credit during the five-year repayment period. The Gordons decided that this tradeoff did not suit their circumstances at the moment.
“Given our situation, we don’t feel that option is the best fit for us right now, as we want to maintain some flexibility in case we need access to credit,” they said in an email.
Their decision illustrates a difficult balance for households managing debt. A lower payment can provide breathing room, but a repayment plan may also limit access to credit. For a family dealing with job uncertainty, preserving flexibility can feel essential, even when the existing debt load is costly.
The couple also spoke with a credit union about alternatives. They learned that they would need to improve their credit scores before qualifying for either a personal loan with a favorable interest rate or a balance-transfer card. Such a card could potentially give them as long as 21 months to repay a transferred balance without interest.
For now, raising their credit scores has become a key goal.
“We want to get our score high enough to get a balance transfer card,” Mariza said.
A Financial Reset in Progress
The Gordons’ situation shows why debt repayment often requires more than a single solution. Credit card balances, minimum payments, credit scores, employment changes and future goals can all affect which option makes sense. A plan that looks attractive on paper may not be the right fit if it removes flexibility a household believes it needs.
The couple is still at an early stage of their financial reset. They have started identifying their priorities, comparing repayment possibilities and defining the future they hope to build. Their next steps will determine whether those goals—homeownership, entrepreneurship, retirement savings and room for travel—can gradually replace the paycheck-to-paycheck cycle that has weighed on them.
Related Reading
Frequently Asked Questions
What is One couple wants to stop living?
One couple wants to stop living is the main topic of this guide. The article explains the context, practical details, and next steps readers should understand.
Why does One couple wants to stop living matter?
One couple wants to stop living matters because readers are looking for a useful answer, not just a short summary. Good content should match search intent and help them decide what to do next.